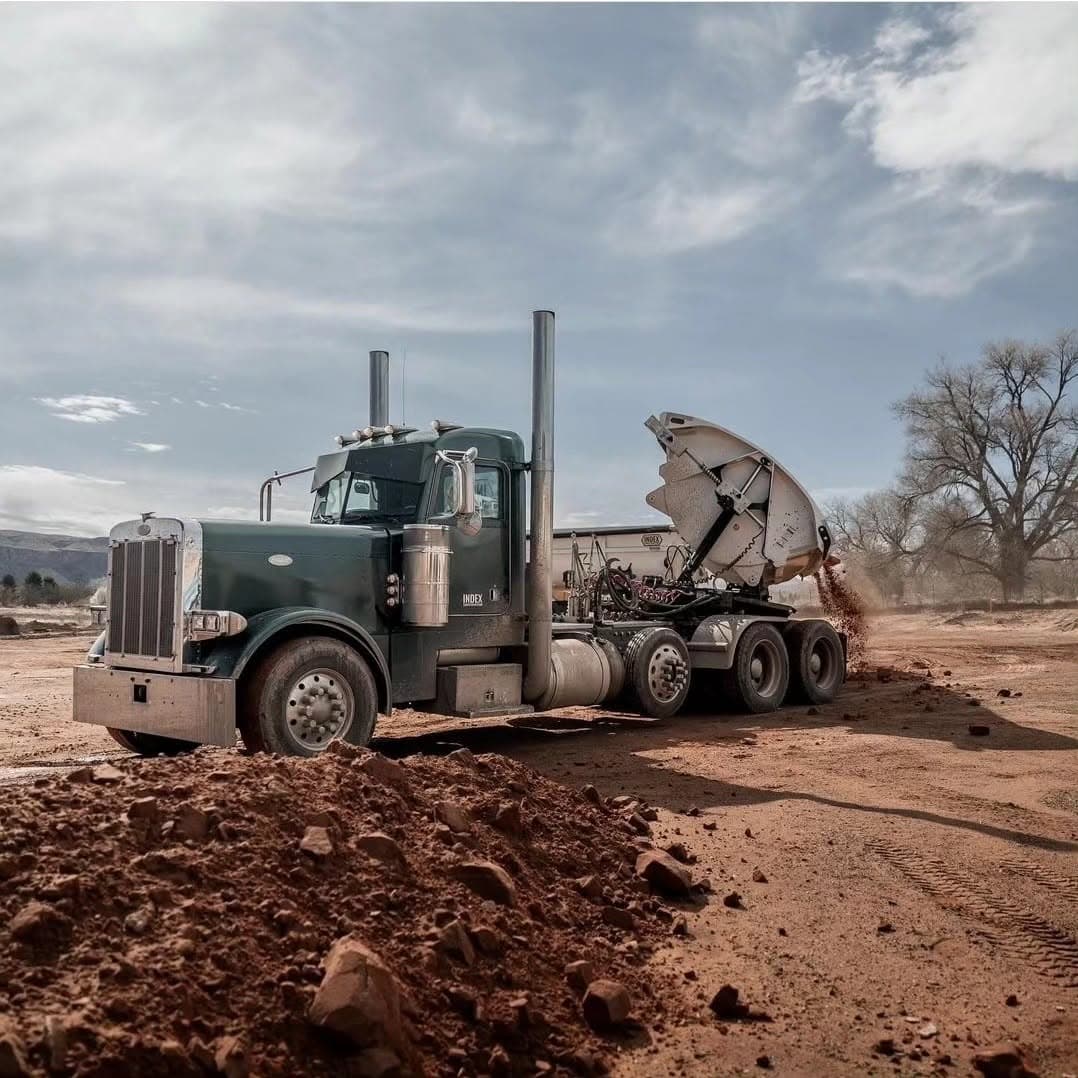

Almost everything written about this online is written by lenders, and almost all of it is about trucks. That is a problem if what you are buying is a $67,900 end dump or a $127,900 side dump, because the lender's article cannot tell you what the equipment costs, what is already baked into the price, or what happens when you buy three of them at once.
This is the same thing from the dealer's side of the desk. Western has been financing commercial trailers since 1983, across four yards, and the terms below are the ones we actually publish.
What a commercial trailer deal looks like
Trailers sit in an odd spot. They are too expensive for a business line of credit and too specialised for a bank that writes auto loans — a local branch generally will not write commercial equipment paper at all. So the deal runs through equipment lenders, and it looks like this:
- $0 down is available for qualified buyers. Not everyone, and not on every unit, but it is a real structure and not a teaser. You can also put money down to shape the payment; the less you put down, the more cash stays in the business.
- Terms run from 12 months to six years. Six-year money on a trailer that will work for fifteen is a very different calculation from six-year money on a truck.
- All credit types are considered, and approval is based on the full financial picture rather than a score alone. Newer businesses and startups can qualify — lenders will look at industry experience, the business plan and available collateral.
- Used equipment finances too, with terms that vary by the age and condition of the unit.
- No early payoff penalty. If the season goes well and you want the note gone, you keep the savings.
Pre-approval is often same day. Full approval typically takes 24 to 48 hours. The application takes about ten minutes.
One credit file, several lenders
Here is the part the lender articles will not tell you, because it is not in their interest to.
One credit file, several lenders, one set of paperwork. When you apply directly to a lender, that lender either likes your file or it does not, and if it does not you start again somewhere else — with another pull, another packet, another week. A dealer-arranged deal works the other way: our finance team takes one file and puts it in front of multiple lenders, and they compete for it. Ang Fagoaga runs that desk here and stays on the deal from application through approval.
That matters most in the two cases where a single lender is most likely to say no: an owner-operator with a short business history, and a fleet doing something structurally unusual.
Owner-operator or fleet: what changes
If you are an owner-operator, the file is largely you — time in business, the equipment as collateral, and how the payment sits against your revenue. Two structures exist specifically for this and both are published: a 60 to 90 day deferred first payment, so the trailer is earning before the first bill lands, and seasonal skip payments, which put the weight of the schedule in your busy months and lift it in the slow ones. If your work is construction or aggregate, a payment plan built on twelve equal months is fighting your cash flow.
If you are a fleet, the shape of the question changes from "will this be approved" to "how do we structure five of them". Western's fleet programme is written for operators adding two or more trailers in a single deal: bulk-unit structuring, blanket approvals where the lender supports them, and terms scaled to the size of the fleet rather than to the unit. Buyers ask us this one out loud — whether the rate improves when you take more than one at a time — and the honest answer is that the structure improves and that the rate is a lender-by-lender, file-by-file question we will not quote in the abstract.
"Wes was a pleasure to work with and he helped us secure 3 brand new belly dump trailers at an incredible rate. 10/10"
— Steffan D., Western Truck & Trailer customer (Google review, Salt Lake City)
Rate depends on credit, term, the unit and the lender. Nobody can quote you one from a web page, and you should be suspicious of anyone who does.
The 12 percent nobody mentions
Every new trailer price on our site carries the same line: FET tax of 12% included in price. That is the federal excise tax on heavy trailers, and Western publishes prices with it already in.
The excise tax is already inside the price, which means it is already inside the amount you finance. It is not a line item that appears at signing and it is not something you write a separate cheque for. On a $105,900 lowboy or a $164,900 belly dump setup, that is a material share of the number you are borrowing, and it is worth knowing it is in there when you compare our price against a quote that excludes it.
On depreciation and Section 179: we are a trailer dealer, not a tax advisor, and we do not give tax advice. Ask your accountant how the purchase is treated before you decide between financing structures — the answer can genuinely change which one is cheaper for you.
What you are actually financing
The number matters, so here is the real range on our yards:
Equipment | Recent listed price |
|---|---|
Pneumatic / tank unit (Valew HTK-2000-AC) | $29,900 |
End dump (Ranco ED26-34 / ED32-34) | $67,900 |
Belly dump (Ranco LW21-37-2) | $72,900 |
Side dump (SmithCo SX3-42-34) | $87,900 |
Lowboy (Choice 355NG) | $105,900 |
Side dump (SmithCo SX5-49-38) | $127,900 |
Side dump (SmithCo SX6-53-40) | $142,900 |
Belly dump lead-and-pup pair (Ranco "10 Axle Setup") | $164,900 |
Crude transport (Dragon 11000 DC) | $193,900 |
All prices include the 12 percent federal excise tax and all move with stock and build spec. In-stock units ship in days; a factory build runs 8 to 16 weeks — which is worth knowing before you start an approval, because approvals do not sit open indefinitely.
Financing is available nationwide even though the yards are in Utah, Nevada, Montana and Texas.
Next step
See what is on the yard, then apply for financing — about ten minutes, no obligation — or call (888) 615-1388 and talk to the finance team before you apply. Tell us the unit, the term you want and roughly where your credit sits, and we will tell you what is realistic before anyone pulls anything.
Frequently asked questions
A trailer is commercial equipment, so it is financed through equipment lenders rather than through a bank's consumer or auto desk. You apply once — with us it takes about ten minutes — and the dealer's finance team puts that one file in front of multiple lenders who compete for the deal. Pre-approval is often same day and full approval typically takes 24 to 48 hours. Structures range from $0 down for qualified buyers to terms as long as six years.
Yes, $0 down is available for qualified buyers. It is not automatic and it depends on your file and the unit, but it is a standard structure rather than a promotion. You can also put money down deliberately to bring the payment where you want it.
All credit types are considered. Approval is based on your full financial picture — time in business, revenue, the equipment as collateral — not on a score alone, and newer businesses and startups can qualify when the industry experience, the plan and the collateral hold up.
The structure gets better. Western's fleet programme is built for operators adding two or more trailers in a single deal, with bulk-unit structuring, blanket approvals where the lender supports them, and terms scaled to the size of the fleet. The rate itself is a lender-by-lender, file-by-file question and cannot honestly be quoted before we see the deal.
Yes. Every new trailer price on our site is published with the 12 percent federal excise tax already included, so it is inside the amount financed rather than a surprise at signing. Compare that against any quote that shows a price before FET.
Yes. Financing is available on both new and used equipment; terms vary with the age and condition of the unit.